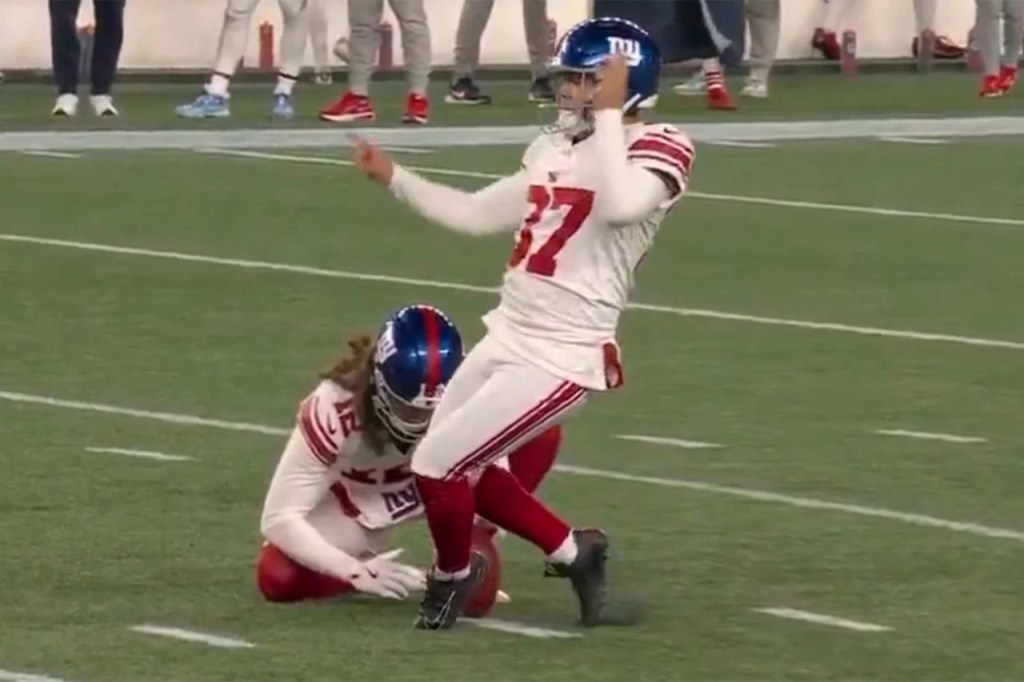
Week 13
TL DR:
- Week 14 is here!
- Believe it or not people, this is the final week of our regular season!
Well folks, we’re here. Another season gone too soon. As we enter our final week of the regular season we still have 3 teams competing for the final playoff slot. By the end of the week only one of Joey, Kate, and Sydney will still be playing…
Week 12 Recap
Alec, Joey, Stefan, George, Sadie & Sydney are the Week 12 winners 🥳
Sam, Kate, Will, Emma, Tony & Rosie/Julia are the Week 12 losers ❌
Joey was the top scorer in a relatively unspectacular week of scoring with 133.8. Kate retains the season high of 165.54 points.
No close ones this week.
The top scoring player this week was AJ Brown, snagging a cool 35.2 points for Stefan.
And now the scores:
Daytona Slurs – 108.1 vs The Better Munhall – 100.36
HouseOfDaDragIcon – 133.8 vs clinton crime family – 79.12
Cape Canaveral Challengers – 114.34 vs Daddy Milkers 85.72
Denver Buckos – 96.04 vs Glizzy Guzzler 85.62
blackstone valley staybehinders – 92.58 vs spooky poopy dookies – 130.24
Lets Go Brandos – 132.64 vs josie schapolitano oyster heads – 97.82
POWER Rankings
And of course, the most important part, the Official post-Week 13 Power Rankingstm
- Denver Buckos – George Roberts-Oakland +0
- Daytona Slurs – Alec Munhall +0
- spooky poopy dookies – Sadie Geauthreaux +1
- Glizzy Guzzler – Emma Costello -1
- Cape Canaveral Challengers – Stefan Mesarovich +0
- HouseOfDaDragIcon – Joey Panell +1
- clinton crime family – Kate McGaw -1
- Lets Go Brandos – Sydney Cairo +1
- The Better Munhall – Sam Munhall -1
- blackstone valley staybehinders – Tony Alves +0
- Daddy Milkers – William Walton +0
- josie schapolitano oyster heads– Julia Napolitano/Rosie Schultz +0
Our 6-7-8 slots are where all the action has been happening and really the only action that matters at this point. Whichever of those three teams wins and/or has better breakers is gonna punch their ticket to the post-season.
From the Office of the Commissioner
🎵 Now Playing 🎵
That’s our Week 13!
We’ve talked a bit about the AI bubble already, broadly sketching out the contours of the situation, particularly in relation to US-China competition. Today I want to focus in on some of the financial instruments that the hyperscalers, data center developers, and private credit firms are using to enable their eye-popping expenditures, in particular “special purpose vehicles” or SPVs.
Fundamentally there is nothing inherently nefarious about an SPV, essentially just a new venture whose ownership is split between the creditors and the company seeking the financing. But these instruments do provide some key benefits that the AI firms have been able to exploit.
Matt Levine provides a very straightforward schematic description:
The problem is:
- The AI buildout should be financed by debt investors.
- Debt investors want to buy debt of the big tech companies, because they are good credits.
- The big tech companies do not want to sell debt, because they are good credits.
This is a very easy problem to solve! This is known technology! What you do is:
- There’s a box, and the box will build the data centers. (Schematically the box is often a “special purpose vehicle” or a “joint venture,” though in some cases the box is an actual public company but not a huge software company.)
- The big tech companies promise to make some payments (rental payments, etc.) to the box. These payment obligations are not “debt,” in the sense that the tech companies’ accountants decide that they do not count as debt on the companies’ balance sheets, and the credit ratings agencies decide that they do not count as debt for credit ratings purposes.
- The box goes out and sells debt to investors. The pitch to investors is “the big tech company promised to make payments to this box, and the box will pass those payments along to you, so if you think about it the debt of the box is just as good as the debt of the tech company.” And the investors believe that.
“[…]companies like Meta, which can raise money from banks at low rates any time they want to, increasingly choose … not to. Instead, they turn to private investment groups—private equity, essentially—who can create custom financing for the project. And for which the company pays a significant premium over investment grade interest rates […]
So, why would an investment-grade company agree to do that? […]
By structuring it this way, via special purpose vehicles (SPVs) in which they have joint ownership, companies like Meta don’t have to show the debt as their debt. It is the debt of those guys over there, that SPV. Not us. Granted, they retain shared control, and they get to use the AI data center, and nothing there happens without their say-so, but still. It’s not ours.
This is accounting trickery, of course.”
So the most key feature of these vehicles is that they allow a company, like Meta in Kedrosky’s example, to launder debt obligations away from their balance sheet. This has the effect of preserving credit ratings for these companies, but you don’t need to think too long about how that could possibly cause problem down the road…
The most obvious of which is that this game of three-card monte with debt obligations makes it much more difficult to assess risk. While investors and ratings agencies aren’t stupid, they are often willing to go along with the trick. But without the risks surfaced in obvious ways, the likelihood of a distress event increases.
Kedrosky helpfully identifies a couple additional issues in his piece: overbuilding and asset-liability mismatches.
The overbuilding issue seems obvious on it’s face; nearly all of these expenditures are premised on lavish estimates about currently unrealized demand for not yet extant products. But in particular, these instruments contribute to overbuilding by artificially deflating the cost of capital for the projects, thereby muddying market signals and further suggesting that there is more demand that actually exists.
Asset-liability mismatches are more relevant to the creditor side of the agreement, where investors with long term liabilities such as insurers face risks by committing assets to concentrated, illiquid bets (like a data center) when they would normally be expected to make diversified, liquid bets that would enable them to more easily manage losses in a downturn.
So even just looking at one piece of the financial engineering involved in this bubble we are able to find myriad risks and start to identify some of the actual mechanisms of how the house of cards can (will) come tumbling down.
The cracks have already begun to show. Oracle, one of the most aggressive spenders, has seen tumbling stock prices throughout November and into this month and after the the release of Google’s latest model, OpenAI released a company-wide “Code Red” memo.
In other areas of the economy, the rot has started to reach the surface. There have been a spate of stories in recent months about “failures” in the private credit market, particularly those of First Brands, an auto-parts supplier and Tricolor, an auto lender. While these two particular stories are very much characterized by some egregious fraud, the underlying economic motivations of these “late cycle accidents“, as Apollo Global Management chief executive Marc Rowan euphemized, are the same that are driving the outrageous AI expenditures. Overcapitalized lenders desperate for returns are willing to throw money down whichever hole appears in front of them promising to put it to good use. The fraud of Tricolor and First Brands means they’ve blown up a bit ahead of the pack, but as JPMorgan Chase CEO Jamie Dimon pointed out, “My antenna goes up when things like that happen, and I probably shouldn’t say this, but when you see one cockroach, there are probably more… Everyone should be forewarned on this.”
That just leaves the matter of timing the correction, a fools errand if there ever was one…
So my money is on the first half 2026. My gut tells me Spring, April or May, so my brain wants to go with February or March. The narrative has become unmaintainable and general sentiment appears to be quite rancid. We’re in a bit of a lame duck period and I’d bet on a relative detente through the end of 2025 but once we’re back in January I think the gloves come off.
NVIDIA CEO Jensen Huang recently went on Rogan, which seems about as good of a signal that we’ve hit the peak as any…
Until you remember he signed a woman’s bra at a trade show over a year ago.
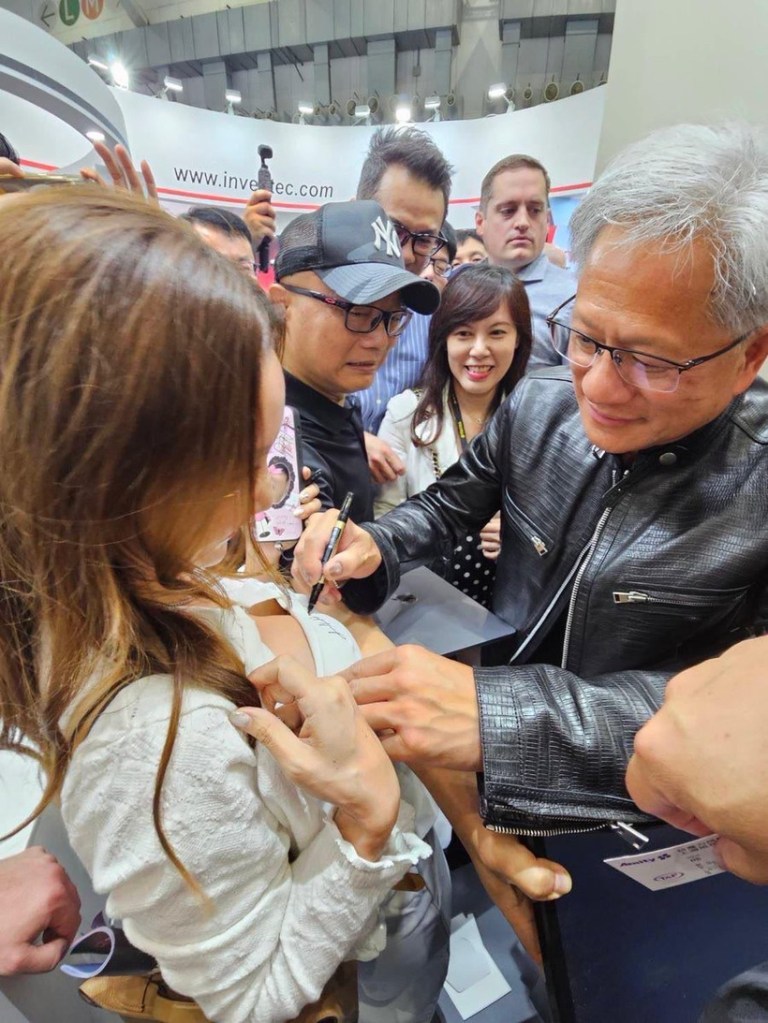
So really who knows, maybe this time capital does finally achieve escape velocity, unmoors the human experience from physical reality, and propels us into an unimaginable post-scarcity, post-mortality world.
Perhaps more likely is that a lot of people go bankrupt, but who knows, I’ve always been a hater.
~~~
You all suck
~~~
Love & Warmth,
Alec


Leave a comment